A major purchase does not always involve acquiring a single item. It may include a main product, delivery, installation, accessories, initial services, maintenance, or expenses whose exact amount will only be known later. When receiving a bundled quote, it is easy to treat all these line items as a single need and consider financing the full amount. However, financing a bundled purchase requires separating decisions with different levels of urgency, duration, and usefulness.
The goal is not to assume that financing is always advisable or inadvisable. It is to understand what is actually being paid for, which part makes it possible to use the item from day one, and which part could be reduced, covered with savings, or left until later. A clear breakdown also makes it easier to compare quotes and better understand the repayment commitment before signing.
What a bundled purchase is and why it is worth breaking it down
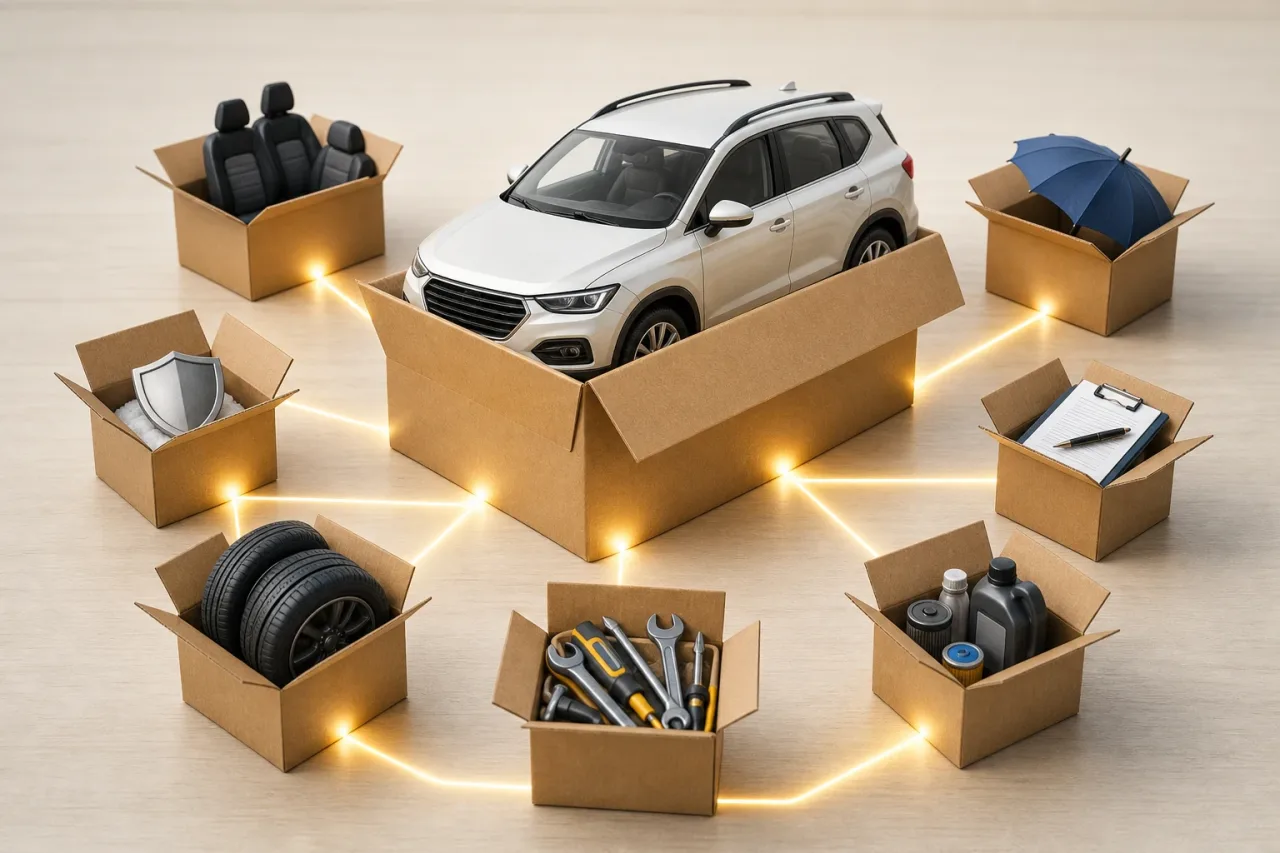
A bundled purchase brings together several elements in a single transaction. For example, purchasing a vehicle may include additional equipment, insurance, paperwork, or maintenance. A move may include transportation, assembly, furniture, and minor repairs. Equipment for the home or for professional use may add installation, supplies, training, and service extensions.
The total price can conceal the fact that the line items do not serve the same purpose. The main product may be needed immediately, while an add-on improves the experience but does not prevent its use. Likewise, an installation cost may be essential, but an estimated contingency is not the same as an item that needs to be purchased now.
When everything is grouped into one figure, extras may seem insignificant compared with the total. However, if they are included in financing, they may also generate interest or extend the repayment term. In addition, some accessories or services may stop being useful well before the debt is fully repaid.
The layers of the quote: from what is necessary to what is uncertain
Before assessing how to pay, it is advisable to request or prepare a quote with separate line items. There is no need yet to decide whether each one will be paid in cash or through financing. The first step is to understand the cost and purpose of each item.
- Main item: the central good or service motivating the purchase.
- Costs needed to use it: delivery, installation, adaptation, setup, or essential materials.
- Related services: assembly, configuration, training, initial maintenance, or additional warranties, when offered separately.
- Extras and upgrades: accessories, finishes, expansions, or features that provide added convenience, aesthetics, or performance.
- Contingency or reserve: an amount set aside for unforeseen events, scope changes, or expenses not yet confirmed.
This classification is not intended to label a line item as good or bad. An installation service may be essential in one case and unnecessary in another. What matters is documenting why it is included and what would happen if it were postponed. If the provider does not offer a sufficient breakdown, it may be useful to request one in writing and ask which items are mandatory, which can be purchased later, and which have an estimated price.
Essential, worthwhile, and postponable: questions for each line item
A practical way to organize a purchase is to create three scenarios. The functional minimum includes what is essential to have the item and use it safely or properly. The reasonable full option adds elements that provide clear and foreseeable value from the outset. The expanded option includes upgrades, preferences, and extras that can wait.
To classify each item, these questions may help:
- Would this item prevent use of the main product if it is not purchased now?
- Is there a temporary, simpler, or lower-cost alternative?
- What would it cost to delay it, and would that be manageable?
- How long is it expected to remain useful compared with the repayment term?
- Is it a fixed price or an estimate that may change?
- Can it be purchased separately later without significant disadvantage?
Urgency deserves special attention. Something can be desirable and still not urgent. It is also worth distinguishing between an operational need and a preference. For example, if household equipment requires a connection or installation to work, that cost may be part of the functional minimum. By contrast, an aesthetic upgrade or a feature that does not affect basic use will generally fit better within the expanded option.
A single quote simplifies the purchasing process, but it does not replace the decision to prioritize each line item.
Deciding what amount to finance, pay with savings, or postpone
Once the scenarios have been defined, it is possible to assess what amount, if any, makes sense to finance. The answer will depend on income, other commitments, available savings, the stability of the personal situation, and the specific financing terms. Not every purchase needs to be resolved through a single payment source.
In general terms, it is advisable to consider three possible uses separately. The essential portion with a known price can be assessed as a possible financing amount. Small, predictable, and near-term costs can be paid with savings if doing so does not leave the person without room for regular expenses. Postponable extras can remain outside the transaction until funds are available or their need is confirmed.
It is important not to confuse a contingency fund with money automatically intended to expand the purchase. A contingency fund is meant to address plausible deviations, not to justify non-priority accessories. If an amount for undefined unforeseen expenses is added to the loan, there is a risk of turning uncertainty into debt from day one.
How to set aside a separate contingency fund without turning it into an extra
Uncertain expenses are common, especially when installation, minor renovations, transportation, or adaptation are involved. Prudence does not necessarily mean adding a generic amount to the financed quote, but rather identifying the circumstances that could generate an additional cost.
It may be useful to prepare a simple list: what unforeseen expense is being considered, why it might occur, what evidence suggests it is possible, and how it would be covered. If the amount is not confirmed, it should appear as a contingency fund separate from the accepted quote. This helps avoid presenting an estimate as though it were a firm cost.
It is also advisable to set a limit and check whether any contingency funds remain after the purchase is completed. If they are not used, they will not have become an unnecessary debt item. If they are used, it will be easier to verify what they were used for. Keeping communications, revised quotes, and invoices helps maintain that traceability.
The effect of financing small items over a long term
A small line item may seem irrelevant when looking at the monthly payment, but it should be assessed in the context of the total cost and the length of the loan. By adding extras to the financed principal, not only may the payment or term increase: interest costs may also rise, depending on the applicable terms.
Before accepting financing tied to a full quote, it is advisable to review the financed amount, term, payment, total cost of credit, and the consequences of modifying or canceling any included services. Comparisons should be made between equivalent options: the same amount, a similar term, and the same line items. A lower payment alone does not prove that an option costs less, since it may result from a longer term.
It is also reasonable to ask whether you will still be paying for an add-on when it is no longer useful, has worn out, or has lost relevance. This question is especially important for quickly consumed accessories, initial services, or items that can be easily replaced.
Hypothetical example: household equipment with installation and add-ons
Imagine purchasing household equipment that requires delivery and installation. The quote includes the main equipment, removal of the old unit, installation, a service extension, additional accessories, and an estimated amount for a possible adaptation of the space.
The functional minimum could include the equipment, delivery, and installation if installation is necessary for proper use. Removal of the old unit could be included if there is no practical alternative. The service extension would require a separate assessment of its terms, exclusions, and duration. The accessories could be left until later if basic use does not depend on them. The adaptation of the space should not be treated as a final cost until it is known whether it is truly needed and what its price will be.
This example does not indicate which decision to make, but rather how to prevent a single overall figure from erasing important differences. The result may be a smaller amount to finance, a better-identified contingency fund, or the decision to wait before purchasing certain items.
Documentation and checks before signing
The final review should focus on both the quote and the financing agreement. It is advisable to keep the breakdown, verify which line items are mandatory, confirm the services included, and review whether there are terms for modifications, returns, or cancellations.
- Does the quote identify each product and service separately?
- Have mandatory items been distinguished from optional ones?
- Is the contingency fund documented separately from extras?
- Is the total amount to be repaid known, in addition to the payment amount?
- Is the term aligned with the expected usefulness of what is being financed?
- Have the terms for services, warranties, and possible cancellations been read?
Financing a bundled purchase thoughtfully begins by reducing complexity. Separating what is essential, worthwhile, postponable, and uncertain makes it possible to make a more informed decision and avoid having an easy-to-accept quote turn into a larger-than-expected repayment obligation.
Sources and resources
- Loans and credit for bank customers — Banco de España
- Consumer credit information — European Commission
- Financial education portal — Banco de España & CNMV