A budget may appear balanced and yet an installment may come due at a time when the account does not have enough funds. This situation is known as a mismatch between the income date and an installment: the income expected for the month may cover total expenses, but its arrival date does not coincide with the dates when payments are due.
Spotting it early helps prevent returned direct debits, additional charges, repeated use of short-term credit, or rushed decisions. It is not only about how much income comes in and how much is spent, but also when income is received, when each obligation is due, and what portion of the balance is already committed.
What a household cash-flow mismatch is
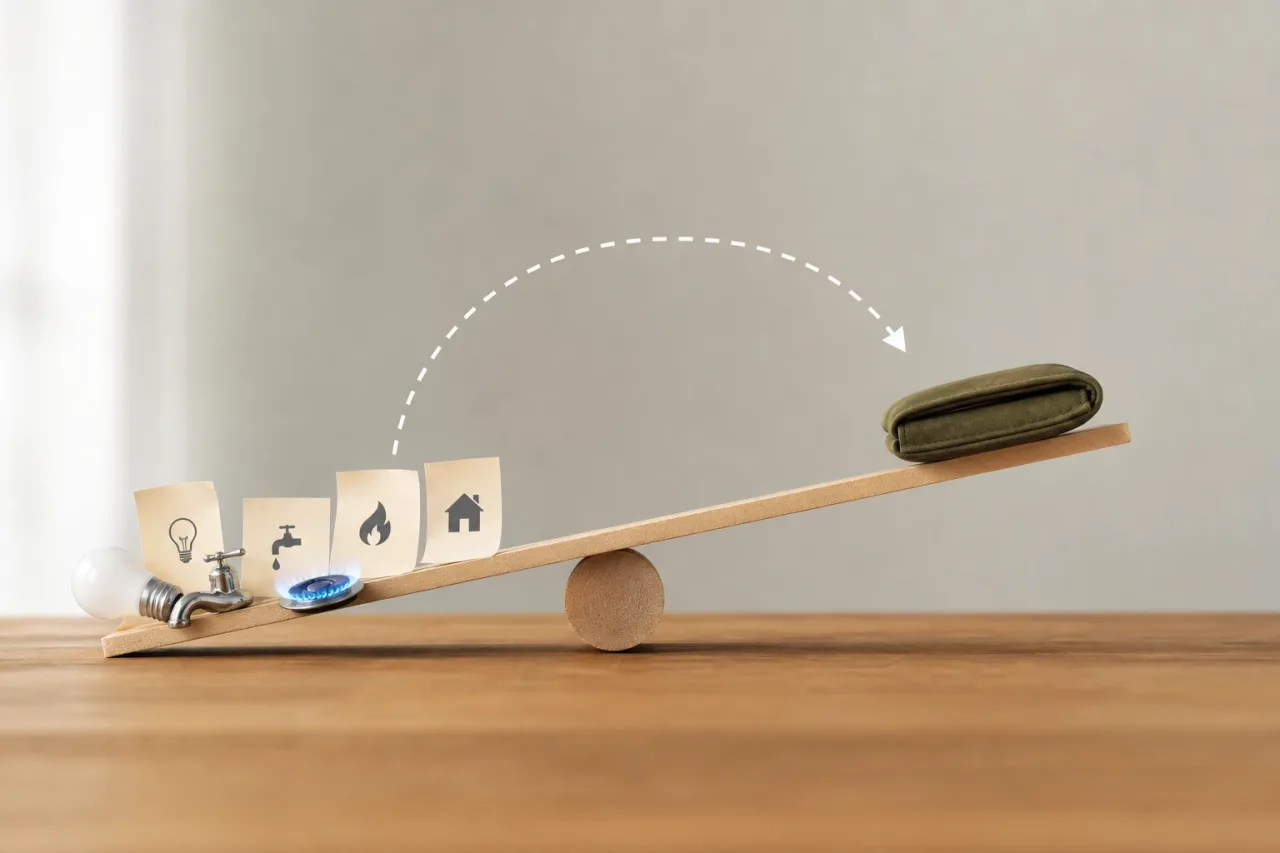
Household cash flow is the money that is actually available to meet payments on their specific dates. A mismatch arises when money goes out before the income that would cover it comes in. For example, a person may receive income at the end of the month but have a loan installment, a utility bill, or a deferred payment during the first week.
This does not necessarily mean living beyond one's means. When the entire month is added up, income may exceed expenses. The problem is temporary: for a few days, the balance may not be enough to meet obligations that are already due or about to become due.
However, a recurring mismatch deserves attention. If every month it forces you to postpone payments, move money away from other needs, or resort to financing, it may indicate that the payment schedule is too demanding for the available liquidity. It may also coexist with a budgeting problem if committed expenses leave too little room.
Monthly budget, available balance, and committed money
A monthly budget answers a general question: if projections are met, does the month's income cover the month's expenses? It is an essential tool, but it is not enough to anticipate a lack of funds on a particular date.
The available bank balance is the amount shown in the account at that time. Nor should it automatically be confused with money that is free to spend. Part of it may be allocated to an installment due tomorrow, a pending direct debit, or essential expenses until the next income payment.
For this reason, it is useful to distinguish three figures:
- Income received: money that has already been received and can be verified in the account.
- Committed money: amounts allocated to installments, rent or mortgage payments, bills, taxes, food, transport, or other upcoming needs.
- Truly free margin: the available balance minus commitments and essential expenses until the next confirmed income.
Expected income, even when it is regular, should not be treated as available funds until it has been credited. This precaution is especially important with variable income, commissions, self-employment work, customer payments, or transfers that may arrive on a date other than expected.
How to create a 30-day timeline
A practical way to locate the problem is to draw up a timeline for the next 30 days. You do not need a complex tool: it can be done in a notebook, spreadsheet, or budgeting app. What matters is arranging each transaction by date, not just by category.
- Write down the current balance of the accounts used to pay bills or installments.
- Record income along with its estimated date, separating income already received from income still pending.
- Include every installment: mortgage, loan, card, deferred purchase, financed insurance, or other recurring obligations.
- Add direct debits and essential payments, such as housing, energy, water, transport, food, or medication where applicable.
- Subtract payments according to their due dates and observe what the balance would be after each transaction.
- Mark the days when the balance would become very low or insufficient before the next income arrives.
It may be useful to keep a cautious estimate. If a bill does not have a fixed amount, note a reasonable figure based on previous bills or leave a buffer. If there is a planned but non-essential purchase, do not assume it can be made until you have checked that it will not reduce the balance set aside for priority payments.
The key question is not only “can I pay this installment this month?”, but “can I pay it on its due date without putting the essential payments that come afterward at risk?”
Classifying payments by flexibility
Once the calendar has been mapped out, classifying cash outflows helps you decide what to monitor first. Not all expenses have the same consequences, payment terms, or possibilities for postponement.
Fixed payments
These are payments with a date and amount that offer little flexibility, or whose non-payment may cause issues. They often include financing installments, rent or mortgage payments, certain bills, insurance, and agreed obligations. When possible, it is advisable to set aside the amount in advance and check the applicable terms before trying to change anything.
Moveable payments
These are expenses that, depending on the provider or situation, may have a payment window, an adjustable date, or an organizational alternative. This does not mean they can be delayed without consequences. Before taking action, it is important to review the contract, the notices received, and the possible costs or effects of a change.
Expenses that can wait
This category includes non-essential purchases, leisure, dispensable subscriptions, or purchases that are not urgent. Reducing them temporarily does not by itself solve a misaligned payment structure, but it can protect the balance earmarked for immediate obligations.
Calculating a minimum operating reserve
An operating reserve is an amount set aside to cover payments and basic needs during the interval between a due date and the next income payment. It does not have to be a fixed figure for everyone: it depends on dates, income stability, essential expenses, and the usual variation in bills.
To estimate it, identify the most sensitive period in the calendar. Add up the installments and bills due on those days, together with the basic expenses needed until the next confirmed income is received. The result provides guidance on the balance that would be prudent not to consider available for other uses.
For example, if an installment and two bills are due between the 3rd and the 15th, and basic transport and food expenses are also needed until income is received, the reserve should account for that entire set. If income is irregular, it may be reasonable to apply an additional buffer without relying on uncertain payments.
Keeping this reserve in a separate account can make organization easier, but it is not essential. It may also be enough to record it clearly and treat it as unavailable money. What matters is not confusing that amount with actual spending capacity.
Hypothetical case: income arrives after the installment is due
Imagine a household that receives monthly income on the 28th. Its total expenses, including installments, fit within that income. However, a deferred-purchase installment is charged on the 5th, and several bills are presented between the 6th and the 10th.
After end-of-month expenses, little balance remains on the 1st. Although the income received on the 28th will make it possible to balance the full month, it will not be available when the installment is charged. The problem is not necessarily the total amount of the installment, but rather the lack of a reserve from the previous income payment to get through the first days of the cycle.
The timeline makes it possible to see whether the adjustment can be achieved by reducing non-essential outflows at the end of the month, maintaining a gradually built reserve, or reviewing the dates and terms of certain payments. If there is no margin even after prioritizing expenses, it is advisable to analyze the full budget and not assume that a new installment will solve the situation.
What to review before adding financing or changing a date
When there is liquidity pressure, taking out more credit or refinancing an obligation may seem like an immediate solution. But new financing normally adds future payments, costs, and a due date that must also fit into the calendar. Covering every mismatch with credit can turn a temporary difficulty into a more persistent burden.
Before accepting an arrangement, it is useful to review the total cost, the number of installments, payment dates, fees, and the consequences of paying late. It is also advisable to check whether the new installment will coincide with other obligations in the days before income is received. A lower monthly payment does not always mean a lower total cost or a better cash-flow fit.
Changing an income or payment date may be possible with some products or services, but it depends on each institution's contractual terms and operating procedures. It should not be assumed, nor should the budget be based on a change until it is confirmed. If requested, it is preferable to do so in advance.
Prudent measures if the mismatch already exists
When facing a current mismatch, the first step is to gather dates, amounts, and the actual balance. Then prioritize essential payments and obligations with the nearest due dates, taking into account the consequences of each missed payment. Avoid making calculations with money that is still pending as though it were already in the account.
Reducing friction also helps: review direct debits, activate balance and due-date alerts, avoid having the same account handle payments without monitoring, and set aside amounts as income is received. If you anticipate difficulty meeting a payment, it may be helpful to communicate it in advance to the relevant provider or institution to find out about the available options and their terms.
Common mistakes include ignoring upcoming bills, spending the balance that was already allocated, relying on income that has not yet been received, and using credit to cover every week of insufficient liquidity. A 30-day calendar and an operating reserve do not eliminate all unexpected events, but they make it possible to distinguish between a one-off delay and a pattern that requires a broader review of monthly commitments.
Sources and resources
- Financial literacy — OECD
- Consumer credit information — European Commission
- Financial education portal — Banco de España & CNMV