Financing is often assessed based on an immediate figure: the monthly payment. It is a necessary figure, but it does not by itself summarize the ability to maintain a debt until its maturity date. A payment that is affordable today may depend on several conditions remaining in place: certain income, a particular household composition, a level of essential expenses, the intended use of the purchased item, or available savings.
The financing continuity test is a preventive exercise for identifying those conditions. It is not intended to predict specific events or imagine extreme scenarios. Its purpose is simpler: to make visible the elements that support repayment and distinguish between those that appear relatively stable, those that may change, and those that depend on factors that are difficult to control.
This approach can provide perspective before taking out a loan, entering into financing linked to a purchase, or making any significant deferred payment. It also helps compare options with similar monthly payments but very different levels of dependence on current circumstances.
What the continuity test is and why the current payment is not enough
The payment reflects the periodic commitment set out in the agreement. However, the sustainability of a debt depends on the relationship between that payment and the rest of the household finances throughout the entire term. The central question is not only, “can this be paid this month?”, but rather, “what would need to keep happening to pay it in an orderly way for as long as it lasts?”
For example, two people may be able to manage the same payment with similar income. One may have stable essential expenses, liquid funds, and an item they will need for years. The other may depend on variable income, shared housing, or a vehicle whose use will change soon. Although the payment is identical, its continuity is not.
The test does not determine whether a decision is right or wrong. It serves to organize information and identify dependencies that may have been taken for granted. It is advisable to review both the full cost of the transaction and the conditions that would make it possible to maintain it.
The five foundations that can support financing
Financing is usually supported by several foundations at once. Reviewing them separately avoids attributing the entire ability to pay to a single figure, such as monthly salary.
1. Available income
Not only the amount of income matters, but also its regularity, source, and the portion remaining after usual obligations. If payment depends on commissions, shifts, seasonal work, self-employment activity, rental income, or other variable components, it may be useful to separate them from the more recurring portion. This is not about assuming they will disappear, but about recognizing how much weight they carry.
2. Household and allocation of expenses
Household composition affects who covers housing, utilities, care, food, and other shared expenses. A current arrangement may change due to cohabitation, separation, relocation, the arrival of dependants, or changes in agreements between household members. Financing may be in one person’s name and still depend in practice on a shared balance.
3. Essential expenses
Basic expenses are not entirely fixed. Housing, energy, transport, food, health, education, or care costs may change. Identifying which ones account for a significant share of the budget makes it possible to see how much room remains without treating all expenses as though they had the same priority or flexibility.
4. The financed item
The usefulness of the item also supports the decision. A car, professional equipment, home improvement, or technology product may no longer fit the need before payment ends: because of a job change, a move, family needs, business developments, or simply a change in use. Continuing to pay for something that is no longer useful can increase the sense of burden, even if the payment does not change.
5. Liquidity and ability to respond
Savings do not replace income, but they can make a difference when there is a temporary mismatch between money received and payments due, or when a one-off expense arises. Other non-credit alternatives also count, such as postponing a purchase, selling an asset that is no longer used, adjusting non-essential expenses, or relying on support that is genuinely available. It is important not to treat money already committed to other immediate needs as savings.
How to create a dependency map
A dependency map involves noting the payment, term, and other known associated costs, then linking them to the conditions needed to make the payment. It can be created in a simple table with three categories: stable, variable, and difficult to control.
- Stable conditions: those with reasonably known continuity in the short term, such as a contractual expense already anticipated or a regular source of income.
- Variable conditions: those whose amount or frequency may fluctuate, such as certain income from work activity, transport expenses, or utility bills.
- Conditions that are difficult to control: those that depend largely on other people’s decisions or external circumstances, such as the continuation of an informal agreement to share expenses.
The same circumstance may fall into a different category depending on the case. The aim is not to label it in absolute terms, but to understand its degree of dependence. After classifying the elements, it may be useful to ask what would happen if one of the variable factors stopped contributing for a limited period. The question does not require calculating an exact forecast: it is enough to check which already identified resources or adjustments would cover that interval.
Financing is usually more fragile when a payment depends simultaneously on several variable elements and there is no clear room to absorb temporary changes.
Reviewing income continuity without making predictions
Assessing income does not mean guessing the future of one’s employment or expecting a problem to occur. It means understanding the current structure of incoming funds and avoiding basing a fixed obligation on assumptions that are still uncertain.
These questions can help organize the review:
- What portion of income comes from recurring sources, and what portion comes from variable components?
- Are there months when incoming funds are concentrated, delayed, or lower?
- Is the payment based on income that already exists or on an expected increase that has not yet occurred?
- Are there other recurring payments that will end or begin during the term?
- Are there professional expenses needed to generate that income that are not being included in the calculation?
Answering these questions does not require turning every possibility into an alarm. The purpose is to avoid mistaking exceptional income for the permanent basis of the budget. If the transaction depends on an unconfirmed future circumstance, gathering more information may provide a fuller picture.
Family, employment, and usage changes
The term of financing may be longer than the stability of the needs that prompted the purchase. For this reason, it is advisable to consider the fit between the payment schedule and the expected period of use of the item. A move may reduce the need for a vehicle; a change of role may alter commuting; a renovation may become less of a priority if the home changes; equipment may no longer be suitable for a particular activity.
The potential evolution of family and household responsibilities also deserves attention. There is no need to develop detailed hypotheses. It may be enough to identify known commitments, changes already underway, or informal arrangements that are essential to making the current budget work.
This review is particularly relevant when the item has ongoing costs in addition to the payment. Maintenance, insurance, utilities, fuel, repairs, or accessories may accompany the financing and alter the actual cost of keeping and using it.
Savings and alternatives in the event of a temporary interruption
Liquid savings can provide room for an unexpected expense or a temporary delay in income, but it is advisable to distinguish them from other resources. An available credit limit, for example, is not equivalent to one’s own liquidity because it may add new debt and costs. Similarly, selling an asset is only an effective alternative if it can be done quickly and without affecting essential needs.
Before signing, it is useful to identify which alternatives do not require taking on new debt. These may include delaying the purchase, choosing an option with a lower total cost, allowing more time to save beforehand, or temporarily keeping the item that is intended to be replaced. These are not universal answers, but rather possibilities that make it possible to compare the commitment against more than one timeline.
How to reduce fragility before entering into financing
Fragility does not depend only on the payment. The amount financed, the term, the down payment, the payment schedule, and the contractual terms can change the dependence on future circumstances. A larger down payment reduces the outstanding amount, although it requires retaining sufficient liquidity for other needs. A longer term can reduce the periodic payment, but it extends the obligation and may increase the total cost depending on the applicable terms.
It is also advisable to review whether there are upfront payments, final payments, linked products, fees, insurance, or other costs that affect the budget. Comparing the full payment schedule with the expected period of use of the item helps avoid looking only at the first month.
The room to decide increases when clear information is available before taking on the commitment. Requesting pre-contractual documentation, reading the terms, and understanding what happens in the event of date changes, early repayment, or default makes it possible to assess the transaction with greater context.
Hypothetical case: same payment, different continuity
Imagine two purchases with a similar monthly payment and a similar term. In the first, the item will be used for a stable need, the income covering the payment is recurring, and the budget retains savings after essential expenses. In the second, the payment is covered by combining variable income with an informal sharing of household expenses, and the item may cease to be used if an upcoming job change is confirmed.
The difference is not in the amount of the payment, but in the conditions that must remain in place. The second purchase involves more dependencies that would be worth clarifying: the timing of the job change, the continuity of variable income, the cost of using the item, and the availability of resources if the allocation of expenses changes. This analysis does not require a particular conclusion, but it shows where more information is needed.
Signs to pause and review the information
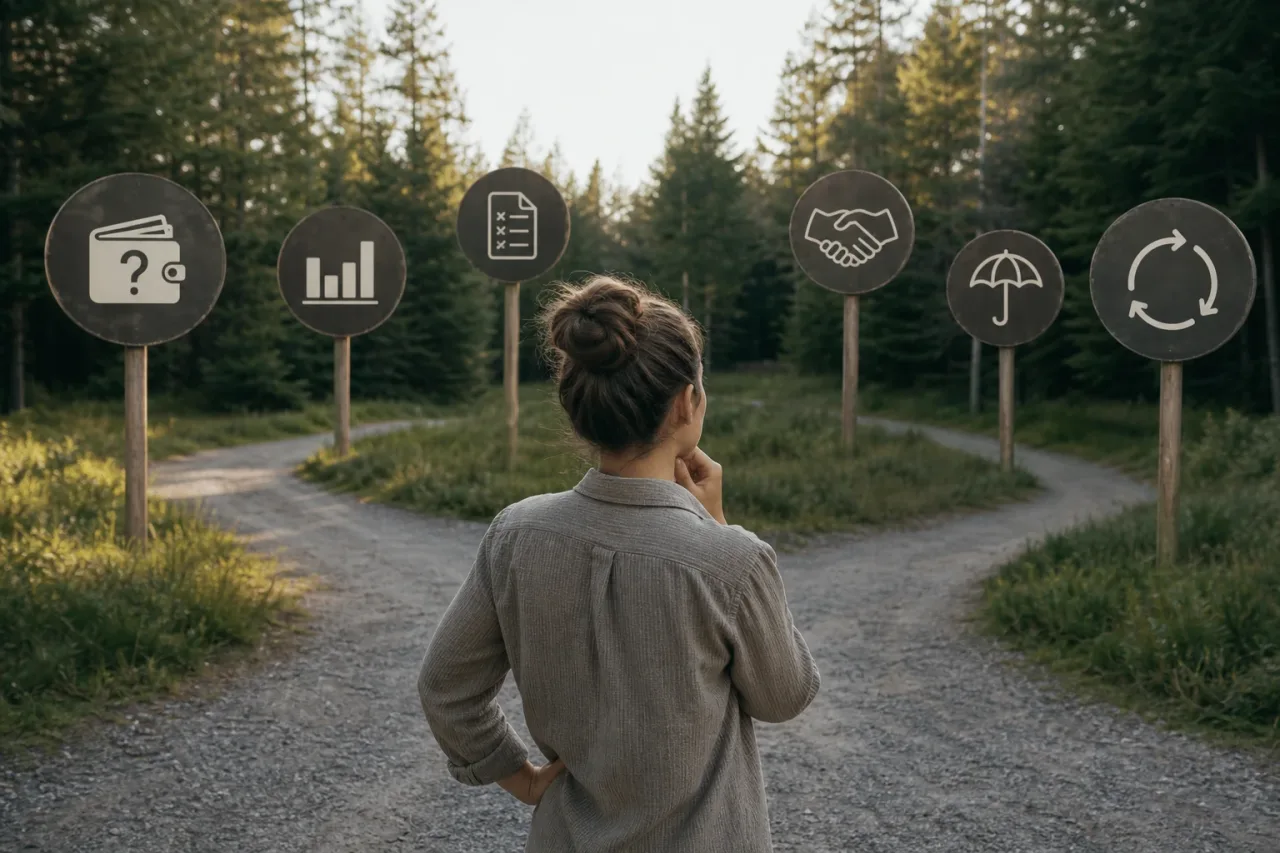
It may be reasonable to temporarily pause the decision when the total cost is unknown, the payment only fits in the highest-income months, the budget omits essential expenses, the purchase depends on informal arrangements, or the use of the item is uncertain for a significant part of the term. It also warrants review if the only response to an unforeseen event would be to take on another debt.
The continuity test does not seek to eliminate all uncertainty, which is impossible in any commitment with a duration. It seeks to prevent a fixed obligation from relying on invisible assumptions. By making the foundations of financing explicit, it becomes easier to compare alternatives, ask questions, and decide with more organized information.
Sources and resources
- Financial literacy — OECD
- Consumer credit information — European Commission
- Financial education portal — Banco de España & CNMV