Financing recurring expenses can seem like a convenient solution when a bill arrives at a time of limited cash flow. However, splitting the payment for an unexpected repair is not the same as paying in instalments for insurance, a utility bill, tuition, or a subscription that will be charged again within a few months. The main difference is not just the amount: it is whether the outstanding debt will overlap with the next due date.
Before accepting a deferred payment arrangement, it is worth viewing the expense as part of a cycle. The aim is not to decide that financing is always appropriate or inappropriate, but to check whether deferral solves a one-off mismatch or simply pushes a bill into next month, adding another instalment to the budget.
What makes an expense recurring and why it should not be assessed in isolation
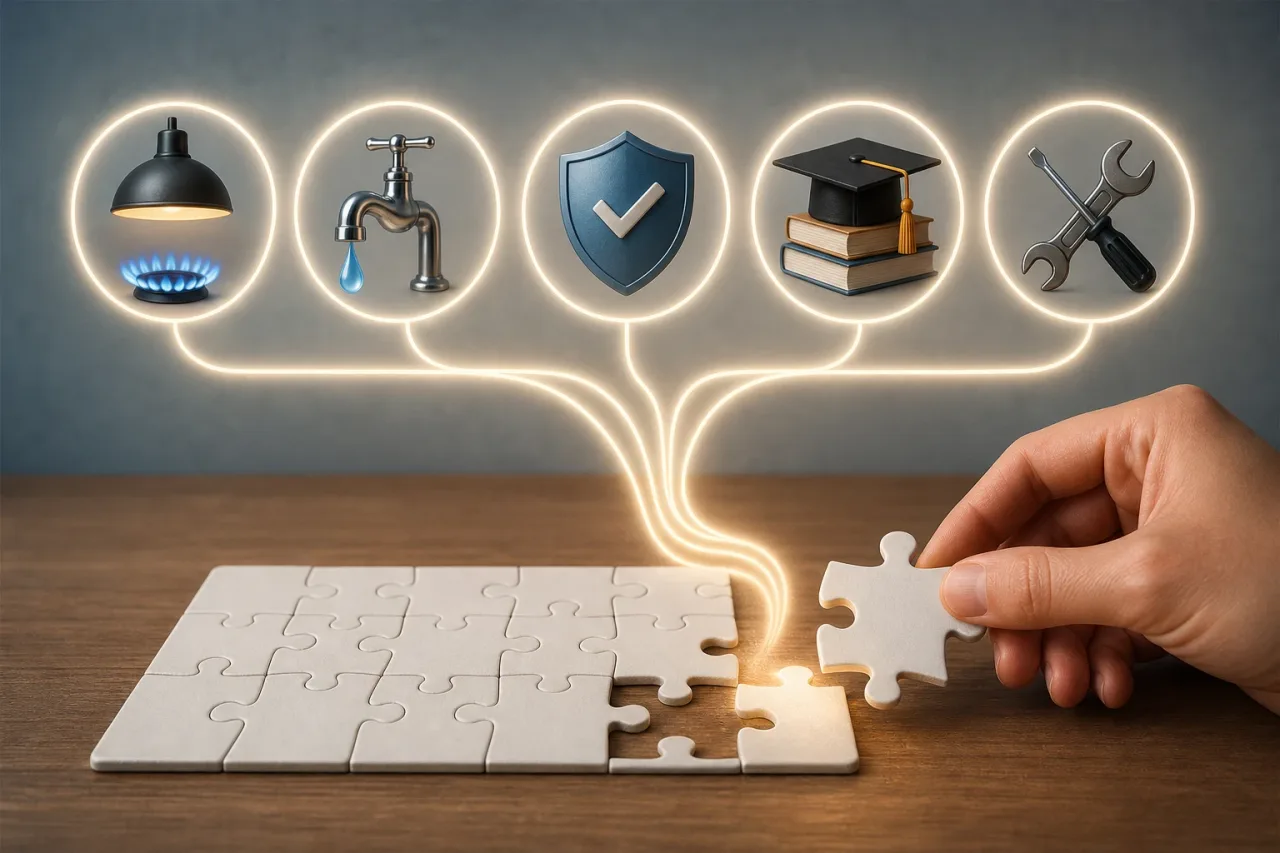
A recurring expense is one that repeats at a predictable frequency, even if its amount is not identical every time. It may be monthly, quarterly, half-yearly, or annual. Household utilities, insurance premiums, certain education fees, scheduled maintenance, or service renewals are common examples.
Predictability is the relevant characteristic. Even if the exact figure of the next bill is unknown, it is usually possible to anticipate that it will arrive and estimate a reasonable range based on previous bills, contracts, or current terms.
For this reason, a recurring bill should not be assessed as a one-off purchase. To understand its actual effect, it is necessary to consider at least these factors:
- Frequency: how often the payment recurs.
- Due date: the deadline and the time available before consequences arise from non-payment.
- Length of the instalment plan: how many instalments will remain to be paid and on which dates.
- Total cost: interest, fees, linked insurance, or other charges that may apply.
- Future repayment capacity: the money that is likely to be available when obligations overlap.
An urgent home repair may be exceptional, although it is sensible to plan for maintenance. By contrast, an annual premium or a monthly bill is part of the normal structure of the budget. Repeatedly financing a structural expense may indicate that the usual budget is not covering all the year’s actual expenses.
The risk of overlapping instalments
Overlap occurs when a new bill for the same item arrives before the previous one has been fully paid. At that point, the household may face the new bill in full, new financing, or both, while still paying earlier instalments.
For example, if a bill that recurs every six months is split into eight monthly instalments, it is likely that two instalments will still be outstanding when the next cycle arrives. This does not necessarily mean there is a problem: it may be manageable if there is a stable margin in the budget. But it does require calculating it in advance.
The risk increases if other recurring expenses are also deferred. Several small instalments may seem easy to manage separately, but together they reduce the money left for food, housing, transport, unexpected expenses, and upcoming due dates. In addition, if a deferred payment option has a cost, the total expense will be higher than the original amount.
The key question is not just “Can I pay the first instalment?”, but “Will I be able to pay this instalment, the next bill, and the rest of my commitments when they overlap?”
The four-question test before splitting a recurring expense
This simple test helps organise the decision. It is best to answer it in writing, using approximate dates and amounts, rather than relying only on the feeling that the payment will be manageable.
- How often does this expense recur? Note the next known or estimated due date. If the expense is annual, identify the renewal month; if it is monthly, consider the next bill.
- What is the total amount and what will it cost to defer it? Check the amount of each instalment, the number of instalments, and the total amount to be repaid. It is also important to confirm what happens in the event of a late payment and whether there are any related charges.
- Will I finish paying before the next bill? Compare the final instalment with the estimated date of the new charge. If they overlap, calculate how many instalments will coincide with the next cycle.
- What realistic source will each instalment come from? The answer should be linked to expected regular income or to a specific, verifiable adjustment. Relying on uncertain income, unconfirmed refunds, or new financing is not a sound source of repayment.
If any answer is unclear, the prudent step is to gather more information before entering into an arrangement. Clarity about the terms and schedule is especially important when the expense relates to essential needs or to a service whose interruption would have significant consequences.
How to map out the bill, instalments, and next renewal
A monthly calendar can reveal overlaps that are not obvious when looking at only one instalment. It does not need to be sophisticated: a sheet of paper, a diary, or a calendar app is enough. First mark the collection dates for the current bill and its next renewal. Then add all the instalments under the deferred payment arrangement and any other fixed payments already committed.
For each month, note three figures: expected net income, essential expenses, and instalments already committed. Subtract the latter two from the first. The result does not automatically equal money available, since variable expenses and savings for unexpected events may still be missing, but it provides an initial margin check.
It is also useful to set aside a line for the next recurring bill from the first month. If the annual expense is estimated by dividing its amount by twelve, that monthly provision shows whether the household can prepare for the next cycle while paying the current instalments.
Hypothetical case: three ways to deal with the same bill
Imagine a recurring bill for a significant amount that is due this month and will renew in a year. With direct payment, the amount is paid now. The budget faces an immediate strain, but no instalments related to that bill are carried into the following months.
With a short deferral, the amount is divided into a small number of payments, and the final instalment is due well before the next renewal. If the instalments fit within the budget and the total cost is known, this option may spread a temporary mismatch without creating an overlap with the next cycle. Even so, it would be advisable to start setting aside money for the future renewal once the situation stabilises.
With the build-up of two cycles, the term is so long, or it is used repeatedly, that the next due date arrives while earlier instalments are still outstanding. If the new bill is then deferred again, instalments from two renewals may coexist. The issue is not the name of the financing product, but rather that the recurring obligation is financed again and again without a clear path to restoring balance.
Prudent alternatives before turning a bill into debt
Depending on the available terms and the nature of the payment, there are measures that may reduce the need to defer it. Not all will be possible in every case, but comparing them helps avoid deciding under pressure.
- Monthly provision: setting aside an amount regularly for annual, half-yearly, or anticipated maintenance expenses.
- Temporary expense adjustment: reviewing non-essential or postponable items to free up cash flow without compromising essential needs.
- Due-date negotiation: asking the provider whether there are date changes, its own payment plans, or different billing options. Terms should be requested in advance and their cost understood.
- Specific reserve: maintaining, where feasible, a separate fund for insurance, maintenance, or known renewals.
- Reviewing frequency: considering whether another billing frequency better suits the flow of income, always taking into account the total cost and terms.
Warning signs to pause and review the budget
There are situations in which it is worth pausing the decision and reviewing the whole budget before accepting another deferral. Some signs include using credit to pay earlier instalments, not knowing how many payments are still active, depending on unconfirmed income to cover the next due date, or delaying essential expenses in order to keep up with instalments.
It also deserves attention when the same expense is financed at every renewal, when the monthly margin disappears after adding up small payments, or when the total cost of the arrangement is unknown. In these cases, organising all debts, bills, and dates may be more useful than looking for another apparently low instalment. If the situation is difficult to manage, independent professional guidance or local consumer information services may help interpret options and obligations.
Final checklist
Before confirming a deferred payment for a recurring expense, review this list:
- I know the date and estimated amount of the next bill.
- I have read the number of instalments, their dates, and the total cost of deferral.
- I have checked whether there will be outstanding instalments when the renewal arrives.
- I have added the instalments to my fixed expenses for every affected month.
- I have a realistic payment source for each due date, without relying on new financing.
- I have compared the option with setting aside money, a temporary adjustment, or asking the provider.
- After paying, I retain room in my budget for essential needs and reasonable unexpected expenses.
Financing recurring expenses requires looking beyond the current bill. A clear calendar, a comparison of the total cost, and a realistic source of repayment make it possible to distinguish between temporary relief and a burden that may reappear before it has been fully paid.
Sources and resources
- Financial literacy — OECD
- Consumer credit information — European Commission
- Financial education portal — Banco de España & CNMV