When you have several debts, deciding which one to pay off first can be just as difficult as working out how much to put toward them each month. Three common methods can help you organize extra money: the avalanche, the snowball, and a combination of the two. None replaces making minimum payments on time or guarantees a particular result on its own. The right choice depends on the costs and balances, as well as which plan you can stick to.
Before comparing strategies, gather the information for each debt and check the current terms. Note the balance, borrowing cost, minimum payment, due date, and any relevant fees or conditions. Then work out how much is left after covering essential expenses and commitments. If there is any money left, that is what you could put toward a priority debt.
The common foundation: cover minimums and organize the details
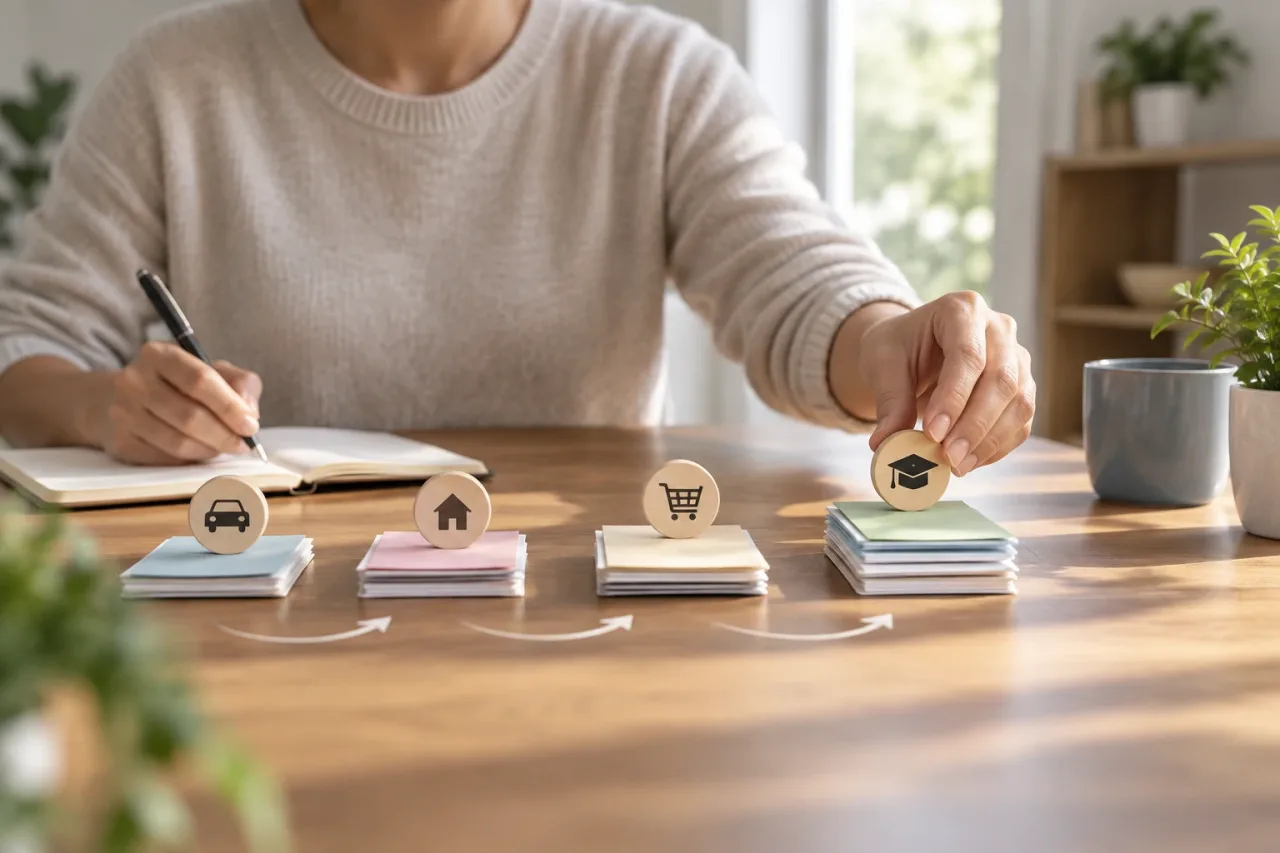
All three methods start with the same practical rule: make the minimum payments on all debts, in line with their due dates and terms, and direct any extra money toward one debt. Once that debt is paid off, add the amount you were putting toward it to the payment on the next debt. Repeat this process until you finish or review the plan.
Making only the minimum payment for a long time can extend repayment and increase the total cost, depending on the terms of the debt. But missing minimum payments to pay another debt faster can lead to charges, contractual consequences, or an impact on your credit standing. If you cannot make the minimum payments, choosing an order among these methods is no longer the priority: consider reviewing your budget and contacting your lenders to learn what options are available.
Your list can also help you spot situations that need special attention. A debt that is overdue, secured by an asset, or subject to significant consequences if you miss a payment should not always be ranked solely by balance or cost. Check the terms of each obligation and consider seeking qualified guidance if you are unsure what consequences delaying a payment could have.
Avalanche method: start with the highest cost
With the avalanche method, after making the minimum payments, you put extra money toward the debt with the highest borrowing cost. Once it is paid off, you direct that amount to the next most expensive debt. To rank debts correctly, check the effective cost and any applicable fees, rather than relying on a single figure or the product name. If the terms change, the order may change too.
A potential advantage is that it reduces the balance generating the highest cost sooner. If other factors stay the same and the extra money is applied as expected, this strategy may reduce the total cost compared with prioritizing a less expensive debt. The exact result depends on rates, fees, terms, changes to the conditions, and payments made; savings cannot be assured without comparing the specific details.
The challenge may be emotional: if the most expensive debt also has a large balance, it may take a while to see it disappear. If that makes you abandon the plan, the mathematical advantage may be less useful in practice. A tracking sheet with updated balances and progress can help keep your gains in view, although it does not replace reviewing the terms.
Snowball method: pay off the smallest balance first
The snowball method ranks debts by balance, from smallest to largest. You make the minimum payments on all of them and put extra money toward the smallest. Once it is paid off, you add the payment you have freed up to the next debt. The name describes the cumulative effect of building up payment amounts as you close out obligations.
A small debt may disappear relatively quickly, providing a clear sign of progress and simplifying your list of payments. For some people, that sense of progress makes it easier to stick with the habit. However, the debt with the smallest balance is not necessarily the most expensive. While you prioritize other debts, a balance with a higher cost could continue to incur charges. That is why the snowball method is not always the lowest-total-cost option.
This method may be a better fit when paying off small balances helps you stay consistent, as long as you make the minimum payments and do not overlook important risks or terms. Before choosing it, weigh the benefit of simplifying your payments against the potential cost of delaying repayment of the most expensive debt.
Hybrid method: adapt the order without losing your bearings
The hybrid method combines cost and balance. For example, you could pay off a small debt first if its cost is similar to the others, then prioritize the debt with the highest cost. You could also decide that a low-balance debt deserves attention for a specific reason, such as simplifying several due dates, and then return to prioritizing by cost.
Flexibility is useful, but it helps to set clear rules. If you change priorities every month on impulse, it will be harder to track progress and estimate the cost. Decide in advance which situations justify an exception, such as a change to the terms, an overdue debt, or a significant change in your income. Note why you changed the order and when you will review it again.
A hybrid approach can also take income stability into account. If your income varies, committing all your available money to paying down debt faster can leave little room for unexpected expenses. Keeping a reasonable reserve for unforeseen needs and avoiding having to rely on credit again may make the plan more sustainable, even if it delays paying off the debt.
Hypothetical example: how priorities change
Imagine three debts: one with a small balance and moderate cost, another with an intermediate balance and high cost, and a third with a larger balance and low cost. Assuming all are current and there are no special conditions that affect the order, the methods would prioritize them differently:
- Avalanche: Start with the high-cost debt, even though its balance is not the smallest.
- Snowball: Start with the small-balance debt, even though its cost is moderate.
- Hybrid: You could pay off the small debt first to simplify the plan, then tackle the high-cost debt, if that exception is manageable.
The example does not show which method is right for everyone. Comparing them would require factoring in actual balances, costs, minimum payments, due dates, and terms. The same method can produce different results if a rate is variable, a fee applies, or the amount of money available changes.
How to choose and avoid common mistakes
When choosing the avalanche or snowball method to pay off debt, consider both the cost and whether you can stick to the plan. These questions can help you organize your decision:
- Which debt has the highest borrowing cost, including relevant fees?
- Would paying off a small debt soon help you stay on track, or would you rather prioritize potential savings?
- Are the differences between balances and costs large or relatively small?
- How much money is left after essential expenses, and how much do you need to set aside for unexpected costs?
- Are there overdue payments, security interests, or other conditions that mean a debt needs to be reviewed separately?
A common mistake is putting all available money toward the priority debt and having no cash left for a necessary expense. Another is missing minimum payments, forgetting due dates, or using the credit you have just freed up again. If you keep using a credit line while trying to pay it down, the balance may not fall as expected. Also review your statements and confirm how extra payments are applied.
Review the order when your income, expenses, or debt terms change, not only when something goes wrong. Regular reviews let you adjust the extra amount without compromising basic needs and check whether the method still makes sense. The most suitable strategy is not simply the one that arranges the numbers well: it also needs to fit your budget, be easy to understand, and remain sustainable over time.
Sources and resources
- Managing debt and financial difficulties — European Banking Authority
- Consumer credit information — European Commission
- Financial education portal — Banco de España & CNMV