An offer may state that you have been approved for a certain amount, yet the deposit appearing in your account may be smaller. To know how much money you can count on from day one, distinguish the loan amount from any deductions and from the sum you will have to repay.
The net amount received from a loan is, in practical terms, the money that is actually available to you after the loan is disbursed. Reviewing it alongside the payment schedule and the expected total repayment helps you understand the transaction as a whole, without confusing figures that serve different purposes.
Loan amount approved, money deposited, and total to repay
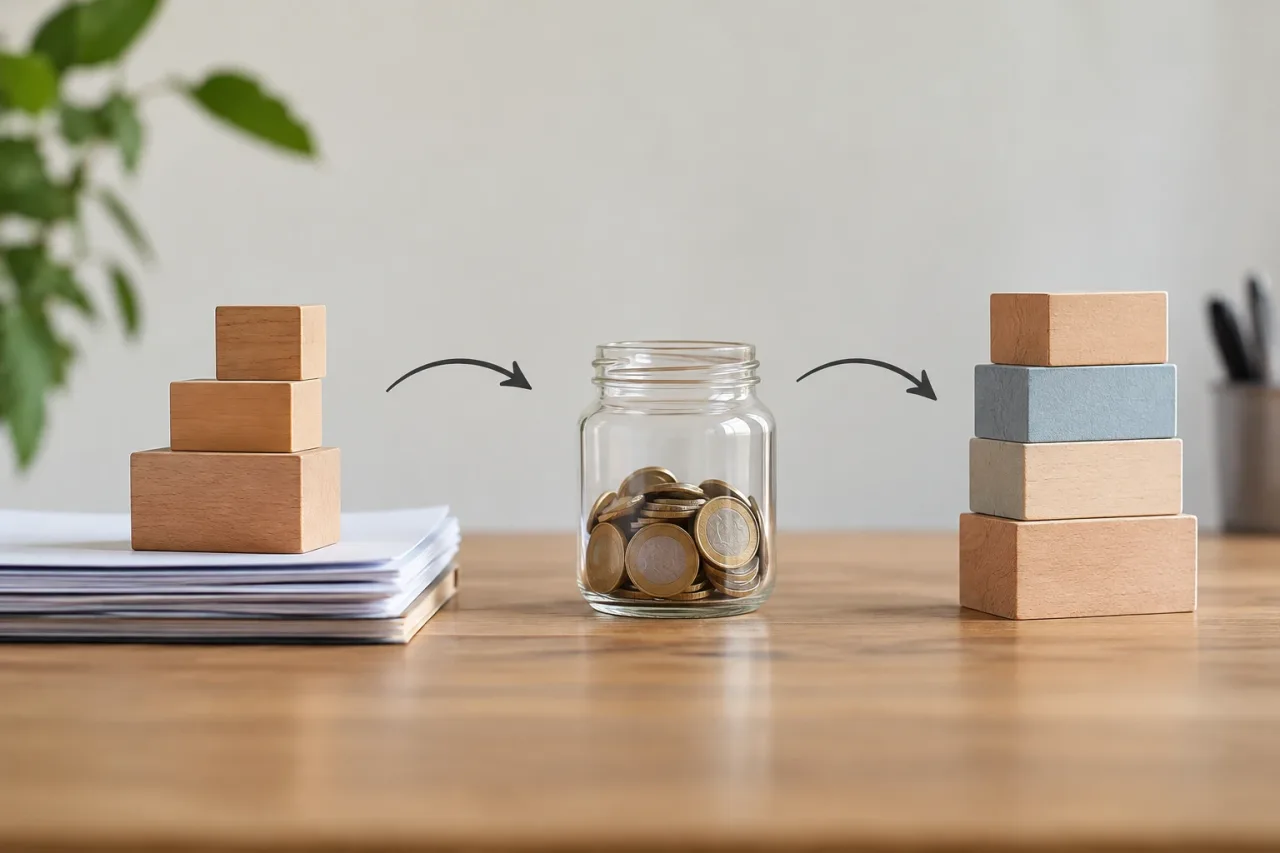
Your documents may show several amounts. Although they are related, they do not mean the same thing:
- Approved or nominal amount: the amount the lender approves or lends, as defined in the contract.
- Disbursement or amount deposited: the money transferred to your account or provided by another method.
- Total to repay: the sum of the payments scheduled over the life of the loan, in line with the agreed terms and schedule.
The total to repay may include the principal and any costs that apply under the contract. It is therefore not necessarily the same as the approved amount. In turn, the amount deposited may be lower than the nominal amount if a charge is deducted upfront. It may also be the same if nothing is withheld at disbursement, even if other costs are charged separately or through instalments.
These differences matter: one figure tells you how much is being lent, another shows your initial liquidity, and the third indicates the expected payment commitment. Comparing only the advertised amount does not tell you how much will be available to you or how much you will pay in total.
What can reduce the initial disbursement
The initial deposit may be reduced by items expressly set out in the contract or offer. Depending on the product and its terms, these could include fees deducted at disbursement or an upfront payment for an associated service. The existence, amount, and treatment of each item must be confirmed in the relevant documents; not all loans apply the same deductions.
Check whether each cost is withheld from the loan amount, added to the financed balance, or charged separately. The difference affects how much reaches your account and may affect what you have to pay later. An amount charged separately does not necessarily reduce the loan deposit, although it may reduce the money available to you after you pay that charge.
Look for a breakdown of the transaction in the offer, pre-contract information, contract, and disbursement receipt. Pay attention to terms such as “gross amount,” “net amount,” “fee,” “expense,” “service,” “withholding,” or “amount to be transferred.” If an item appears without an adequate explanation, ask what it relates to and how it will be charged before relying on that figure.
Hypothetical example: working out the net amount
Imagine a hypothetical offer with an approved amount of 5,000 euros and an initial fee of 150 euros that, according to the breakdown, is withheld when the funds are provided. The deposit calculation would be:
5,000 euros approved amount − 150 euros withheld = 4,850 euros deposited
In this example, the net amount received would be 4,850 euros, not 5,000. The transaction alone does not show how much you will have to repay: to find that out, review the instalments, interest, and any other costs listed in the terms. If, also for illustrative purposes, the contractual total of the payments were 5,480 euros, that figure would differ from both the approved amount and the money received.
The difference between the amount deposited and the amount repaid should not be attributed to a single item without reviewing the breakdown. In this example, 150 euros is withheld before the money is provided and, in addition, the total payments exceed the nominal amount. What accounts for that difference and how it is calculated will depend on the loan terms.
Loan deduction or separate payment
A deduction is subtracted from the disbursement before the money reaches your account. A separate payment, by contrast, is charged in another transaction, for example as a separate debit. In that second case, the loan transfer could equal the approved amount, but the money actually available to you would decrease when the additional payment is made.
Some costs may also be added to the financed balance. That is not the same as deducting them from the initial deposit: you could receive one amount and have to repay a sum calculated on a different balance, depending on what was agreed. Do not assume that a charge is included in the instalment, financed, or deducted; check the documents and ask for written clarification if this is unclear.
To keep the figures organised, list them separately:
- The nominal amount stated in the offer and contract.
- The exact amount to be transferred and the expected date.
- Charges withheld before disbursement.
- Payments charged separately and when they apply.
- The expected total repayment and the instalment schedule.
Useful questions to ask when reviewing the documents
Before counting on a specific amount, check that all the documents refer to the same version of the offer. Check the dates, amounts, and terms, and ask specific questions if you find differences. For example:
- What amount is being approved, and what net amount will be deposited?
- Which items are deducted before the transfer, and which are charged separately?
- Are any charges added to the financed balance? How are they reflected in the instalments?
- On what date will the loan be disbursed, and when is the first payment due?
- What is the expected total repayment according to the schedule provided?
- Could the figures change if dates change, early payments are made, or a payment deadline is missed?
These questions do not replace reading the contract, but they can help you find the relevant figures and resolve ambiguities before accepting a loan. Keep the offer and breakdown you were given so you can compare them with the contract and, later, with the actual deposit and charges.
Checklist for comparing offers
If you are reviewing several options, compare their terms on a consistent basis. Do not compare the nominal amount of one offer with the net deposit of another, or compare a single instalment without considering the term and number of payments.
- Identify the approved amount in each proposal.
- Calculate the net disbursement by subtracting only amounts withheld upfront.
- List separately any charge collected through another transaction.
- Review the payment schedule and the total to repay stated in the documents.
- Confirm whether the figures depend on specific terms, dates, or services.
- Ask for clarification about any item you cannot connect to an amount and a method of collection.
The net money available may be a useful reference when assessing whether the loan covers a specific need, while the total payments help you understand the repayment commitment. Neither figure, on its own, summarises all the terms; consider them alongside the loan term, instalments, and other relevant conditions.
Calculations are no substitute for contractual figures
A calculator or a simple calculation can help organise amounts, but it provides only an estimate when the information is incomplete or provisional. The result may not include charges, date changes, or other terms set out in the offer. In addition, lenders and products may use different names and ways of presenting items.
Before making a decision, compare the money you expect to receive with the final breakdown and the disbursement receipt. Also confirm the total and payment dates shown in the contractual documents. If the figures do not match or a cost is unexplained, ask for a clear answer before relying on an estimate. This will help you distinguish what is being lent, what will be available to you, and what you will be expected to repay.
Sources and resources
- Loans and credit for bank customers — Banco de España
- Consumer credit information — European Commission
- Financial education portal — Banco de España & CNMV